Understanding the Current Mortgage Rate Trends
In recent months, mortgage rates have seen notable fluctuations, prompting attention from potential homebuyers and industry professionals alike. Historically, mortgage rates have been influenced by various factors, including economic growth, inflation, and central bank policies. Understanding these trends requires a comprehensive look at both current data and the historical context surrounding them.
As of now, mortgage rates are exhibiting a rising trend, a significant shift from the relatively low rates witnessed in previous years. For instance, according to the latest reports, average mortgage rates have surpassed 7%, a mark not reached since the 2008 financial crisis. This increase can be attributed to the Federal Reserve’s monetary policies aimed at combating inflation, which have resulted in higher borrowing costs across the economy, affecting the finance sector in particular.
Several factors contribute to the rising mortgage rates. Firstly, inflation remains a pressing concern, with economic data indicating persistent price increases. The Federal Reserve’s response to this inflationary pressure includes raising interest rates to deter borrowing, thereby stabilizing the economy. Additionally, the supply chain disruptions and labor shortages stemming from the global pandemic have compounded inflation, further influencing rates.
Moreover, the overall economic outlook plays a significant role in shaping mortgage rates. As the economy shows signs of resilience, with job growth and increased consumer spending, investor confidence grows, often leading to higher yields on government bonds—an essential benchmark for mortgage rates. Consequently, as lenders face higher costs, they pass these expenses on to borrowers through elevated mortgage rates.
For potential homebuyers, these trends underscore the importance of being informed and prepared. Understanding how factors such as inflation and economic forecasts influence the finance landscape can help buyers make more informed decisions regarding their home purchases. Overall, staying updated on mortgage rate trends is crucial for navigating the complexities of today’s housing market.
Assessing Your Financial Health Before Buying a Home
Before entering the housing market, it is crucial for prospective homebuyers to evaluate their financial health comprehensively. Such an assessment will serve as the foundation for making informed decisions about purchasing a property. One of the primary considerations is the credit score, which plays a significant role in determining mortgage eligibility and interest rates. Lenders typically favor borrowers with higher credit scores, which signal a history of responsible credit management.
Equally important is the debt-to-income (DTI) ratio. This financial metric compares an individual’s total monthly debt payments to gross monthly income. A lower DTI ratio indicates a healthier financial status and enhances a buyer’s chances of securing favorable mortgage terms. Most lenders prefer a DTI ratio below 36%, with no more than 28% of that figure allocated to housing expenses.
Another critical factor in the homebuying process is the amount of savings designated for a down payment. A substantial down payment not only lowers the mortgage amount but can also eliminate private mortgage insurance (PMI), resulting in lower monthly payments. Additionally, having savings set aside for closing costs and possible home repairs can safeguard against potential financial strains post-purchase.
Homebuyers should also review their overall financial health by considering other assets and liabilities. This comprehensive approach allows individuals to understand their financial capabilities better and make decisions that align with their long-term goals in finance. Overall, addressing these elements can significantly impact mortgage approval and terms, enabling buyers to navigate rising mortgage rates effectively.
In conclusion, a thorough evaluation of credit scores, debt-to-income ratios, and savings for down payments is essential for any homebuyer looking to enter the market. This financial assessment is not merely a formality; it lays the groundwork for successful homeownership in today’s fluctuating economic environment.
Exploring Different Mortgage Options
When considering a mortgage, it is essential for homebuyers to understand the various types available. These options can significantly impact their finance situation, particularly in a landscape of rising mortgage rates. The most common types of mortgage loans include fixed-rate mortgages, adjustable-rate mortgages (ARMs), Federal Housing Administration (FHA) loans, and Veterans Affairs (VA) loans.
Fixed-rate mortgages are one of the most straightforward options. They provide homeowners with a consistent interest rate and stable monthly payments throughout the life of the loan, which typically spans 15 to 30 years. This predictability can be beneficial in a fluctuating market. However, the main downside is that fixed-rate mortgages typically start with a higher initial interest rate compared to ARMs.
Adjustable-rate mortgages, on the other hand, offer lower initial rates that can be appealing in a low-interest environment. While the rate is fixed for an introductory period, it subsequently adjusts periodically based on market conditions, potentially leading to increased payments. This option can be risky if rates rise significantly, making it essential for homebuyers to weigh their tolerance for fluctuating payments against long-term housing needs.
FHA loans are another viable option, particularly for first-time buyers or those with less-than-perfect credit. These loans require lower down payments and have more lenient credit requirements. The trade-off, however, can be higher mortgage insurance costs, which can impact overall finance affordability. VA loans, specifically designed for veterans and active military personnel, provide favorable terms including zero down payment and no mortgage insurance. This makes them one of the best financing options for eligible individuals, but they do come with certain requirements that must be met.
In conclusion, understanding the various types of mortgages available and their respective pros and cons is crucial for homebuyers. By evaluating these options carefully, individuals can make informed decisions that best align with their financial circumstances amidst rising mortgage rates.
Timing the Market: To Buy Now or Wait?
When considering the current landscape of mortgage rates, homebuyers face a pivotal question: should they purchase a home now or wait for potential market changes? Experts in real estate and finance advise that this decision should be informed by a thorough analysis of both current conditions and anticipated trends.
Purchasing a home in an environment with rising mortgage rates can pose challenges, yet it also presents unique opportunities. Real estate professionals often highlight that even amidst high rates, the housing market can still yield favorable conditions for buyers. For instance, decreased competition may lead to better negotiations, as some potential buyers withdraw from the market due to their concerns about affordability affected by high rates. According to a recent study, buyers moving forward during these times may find themselves with leverage to explore lower prices or incentives from sellers.
On the flip side, the risks associated with buying in a high-rate environment should not be overlooked. Higher interest rates lead to increased monthly payments, which can significantly impact budget plans. Additionally, there exists a possibility that waiting could allow rates to stabilize or even decline, potentially providing better financing options in the future. However, predicting market trends is inherently uncertain, and potential homebuyers must assess their individual financial situations and long-term plans, weighing the risk of potentially higher prices against the cost of waiting.
In evaluating whether to buy now or hold off, it’s crucial for buyers to consult with real estate and financial advisors who can provide tailored insights. Both the immediacy of current opportunities and the uncertainties of future market shifts necessitate a careful approach to strategizing the timing of a home purchase. Ultimately, a comprehensive understanding of personal financial capability intertwined with market conditions will guide buyers in making the most informed decision.
The Importance of Getting Pre-Approved for a Mortgage
In today’s competitive housing market, acquiring a mortgage pre-approval becomes a fundamental step for homebuyers aiming to navigate rising mortgage rates effectively. This process involves a lender assessing an individual’s financial background, including income, credit score, and existing debts, to determine the amount they are eligible to borrow. By obtaining pre-approval, homebuyers receive a clearer picture of their financing options, which greatly aids their budgeting and overall finance management.
The benefits of mortgage pre-approval extend beyond mere figures; it significantly enhances a buyer’s negotiating power. When presented with a purchase offer, sellers often prefer to deal with pre-approved buyers because it reduces uncertainty. A buyer who is pre-approved demonstrates their ability to secure funding and shows commitment to the transaction. This reliability can be particularly advantageous in a bidding war, where multiple offers may be made on a single property. Sellers may choose to favor pre-approved buyers, knowing they are more likely to close the sale promptly.
Additionally, having a mortgage pre-approval can expedite the buying process. Since buyers have already submitted essential documentation and received a conditional loan offer, the overall timeline from offer acceptance to closing can be shortened. This efficiency is crucial in fast-paced markets where timely decisions often dictate a successful purchase. Ultimately, pre-approval not only aids in financial readiness but also positions buyers more favorably in a competitive landscape where speed and security are essential.
Engaging in the mortgage pre-approval process reflects the applicant’s preparedness to enter the housing market and manage the financial commitments associated with such a significant purchase. As homebuyers aim to realize their dream of ownership amid rising mortgage rates, prioritizing pre-approval is a strategic move that cannot be overlooked.
Strategies for Negotiating Better Terms
Navigating the complex world of finance, particularly in the realm of mortgage lending, requires a strategic approach, especially in times of rising rates. Homebuyers can enhance their chances of securing favorable mortgage terms by employing several effective negotiation strategies. Firstly, it is essential to understand the interest rate landscape. Research different lenders and their offerings to identify competitive rates. This background research not only equips homebuyers with information but also gives them leverage during negotiations.
Another effective approach is to improve your financial profile. Lenders assess a borrower’s creditworthiness through various factors, including credit scores, debt-to-income ratios, and overall financial health. By improving your credit score prior to applying for a mortgage, you can present yourself as a low-risk borrower. This improvement can sometimes lead to better interest rates and terms, as lenders are likely to provide more favorable offers to financially stable applicants.
Homebuyers are encouraged to gather pre-approval letters from multiple lenders. Having pre-approvals in hand demonstrates to potential lenders that you are a serious buyer and gives you the ability to compare offers side-by-side. This strategy not only puts pressure on lenders to match or beat a competitor’s rate but also strengthens your negotiation position. Moreover, consider being flexible with your mortgage terms. For instance, opting for a shorter loan term can often yield lower interest rates, making your mortgage more affordable in the long run.
Lastly, don’t hesitate to ask questions. Clarifying details about various fees and terms with lenders not only demonstrates your knowledge but can also uncover opportunities for negotiation. For example, points or closing costs may be negotiable, which can reduce your overall financial burden. In conclusion, leveraging these strategies can empower homebuyers to navigate the complexities of mortgage finance more effectively, securing favorable terms even in a challenging environment.
Understanding the Impact of Rising Rates on Monthly Payments
As mortgage rates continue to rise, their impact on homebuyers’ monthly payments becomes increasingly pronounced. The significance of these rates cannot be overstated, as they are directly linked to the total cost of financing a home. Higher mortgage rates mean that homebuyers will face increased monthly payments, which could strain budgets and influence purchasing decisions.
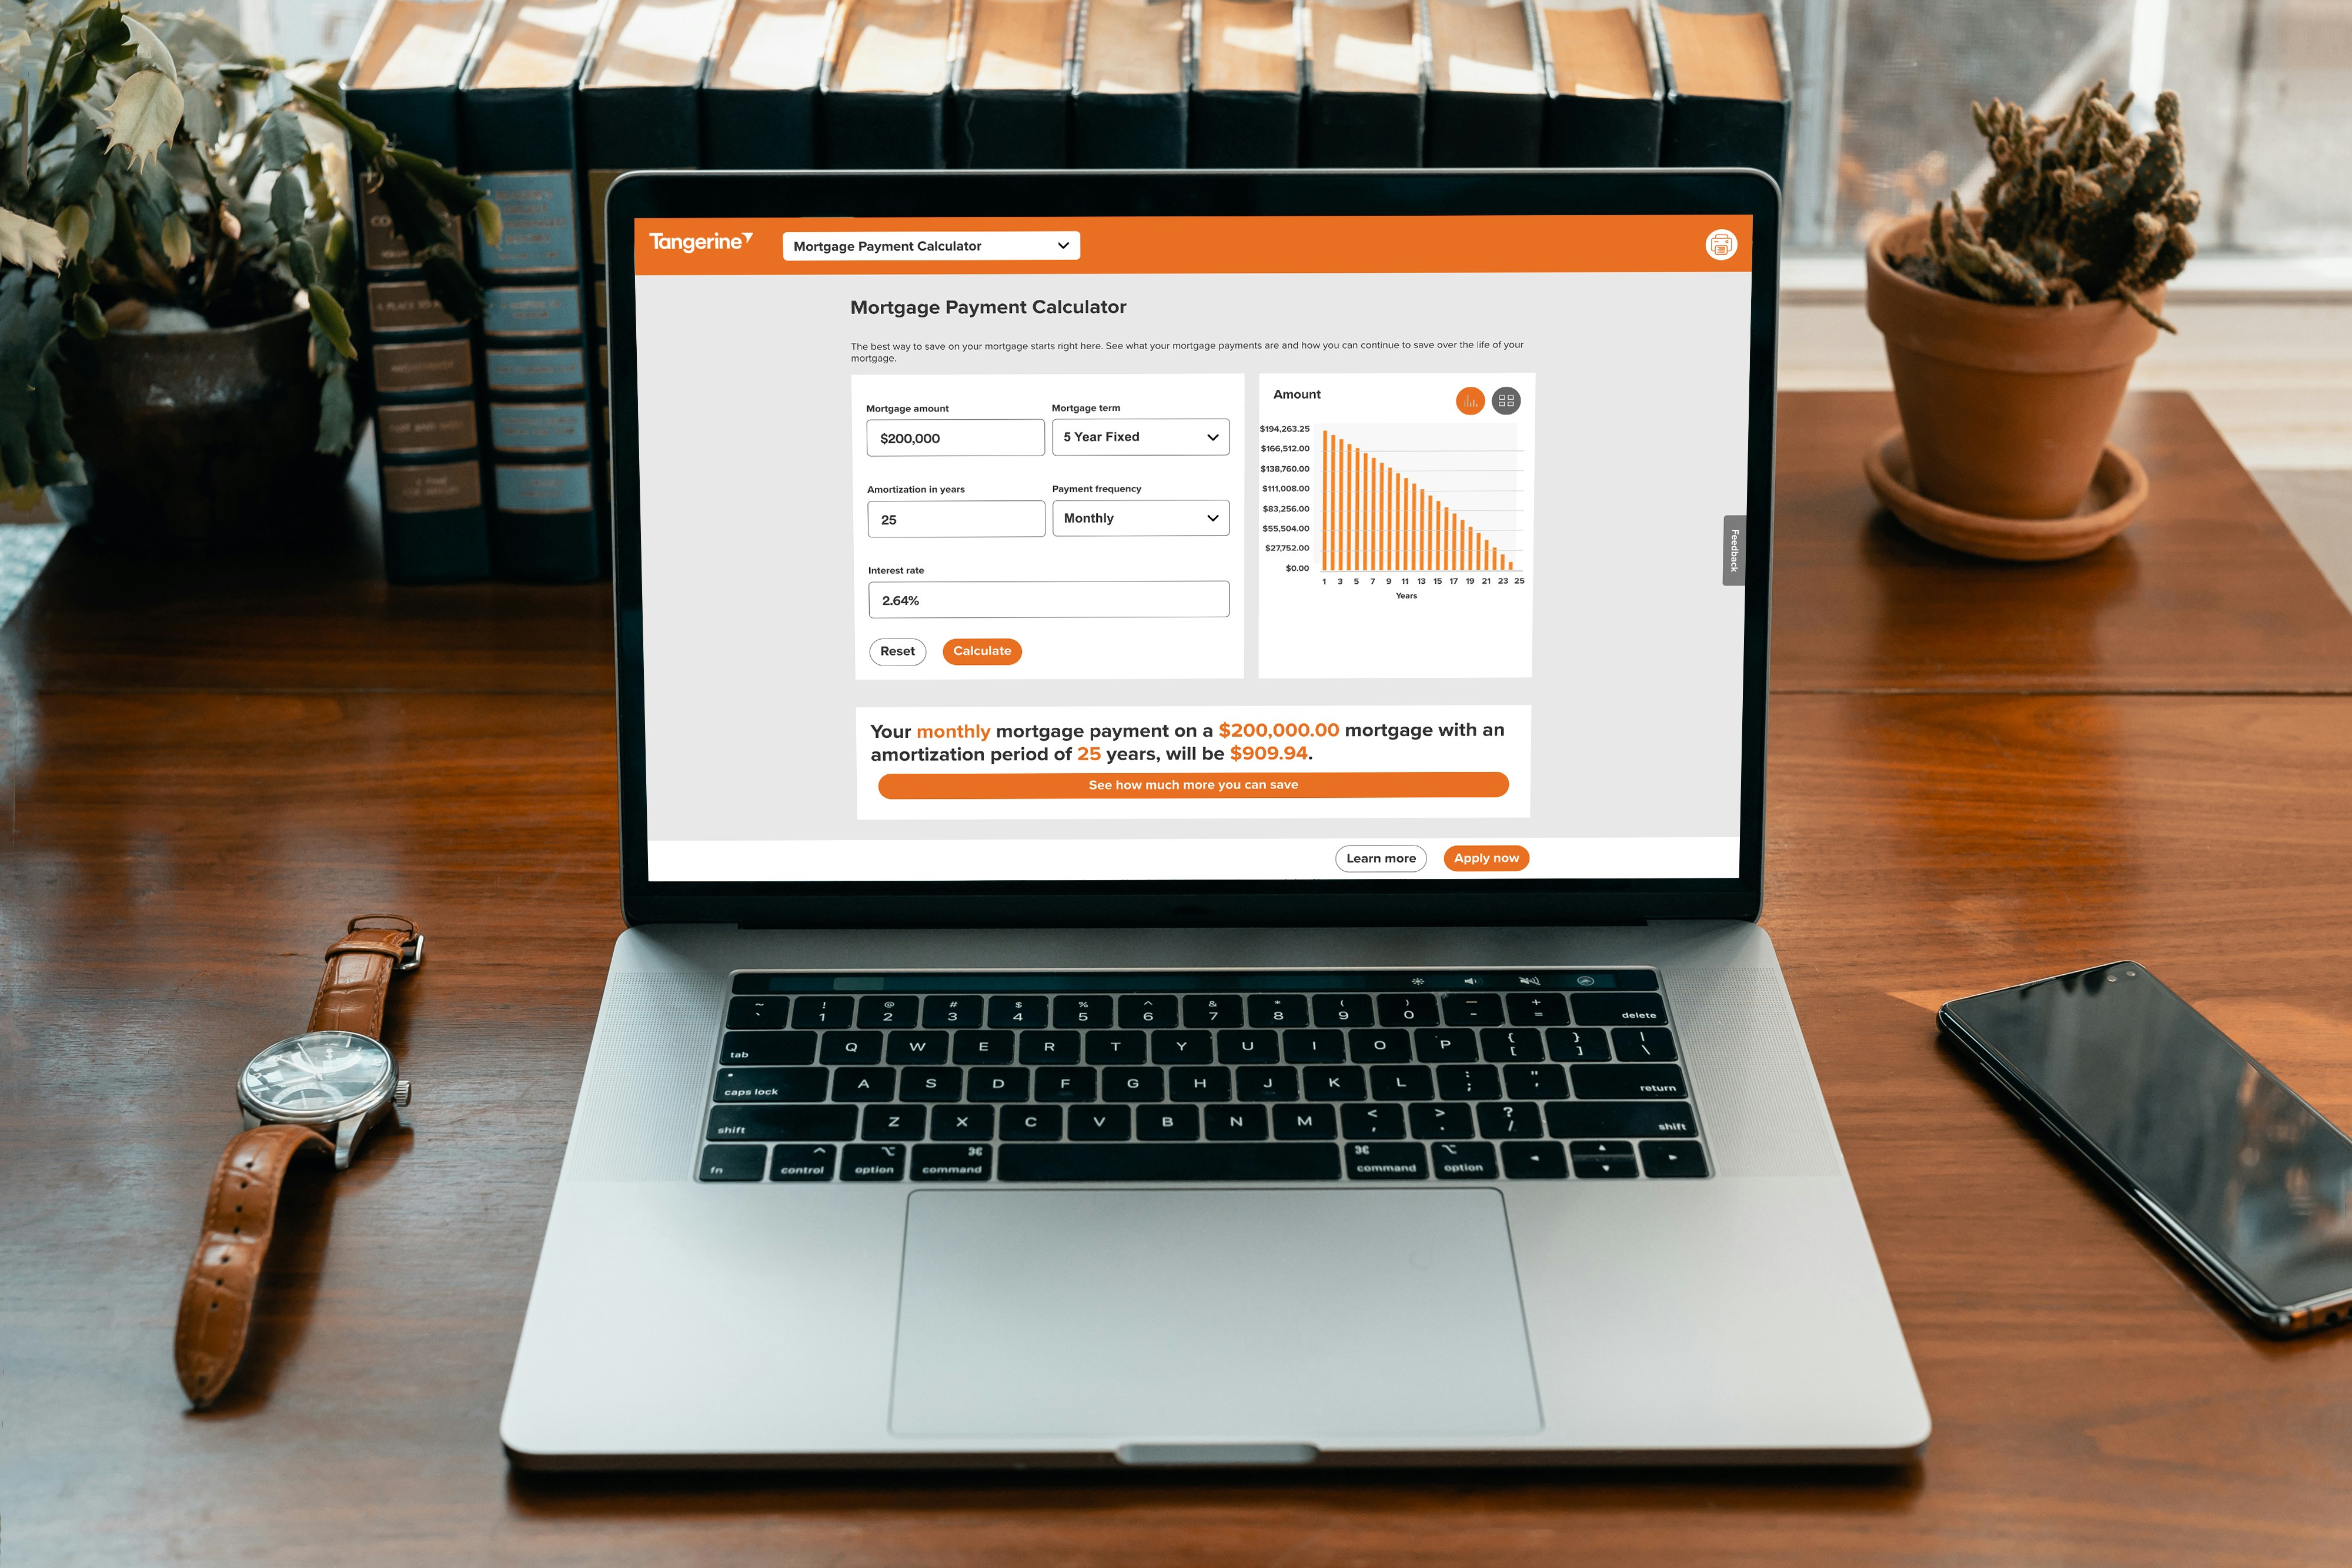
To illustrate this point, consider a hypothetical scenario. Suppose a homebuyer is interested in purchasing a home priced at $300,000. If the interest rate on a 30-year fixed mortgage is currently 3%, the monthly payment on their mortgage excluding property taxes and insurance would be approximately $1,265. Now, if the interest rate were to rise to 4%, the monthly payment would increase to around $1,432. This example highlights that even a 1% increase in the mortgage rate can lead to an additional $167 in monthly payments.
Furthermore, as interest rates climb, the overall loan costs also increase significantly over time. The difference between 3% and 4% may seem marginal on a monthly basis, but over a 30-year term, the total amount paid in interest can be substantially impacted. For the homebuyer in our example, opting for the 4% mortgage could result in more than $60,000 additional payments in interest over the life of the loan.
It is also essential to recognize that the rising mortgage rates can affect the affordability of homes across various price points. When homebuyers encounter higher rates, they may have to adjust their budget downward or reconsider their preferred locations and property types. This shift in market dynamics could lead to increased competition for homes priced within current affordability ranges, resulting in bidding wars and driving prices higher.
In conclusion, understanding how rising mortgage rates affect monthly payments and overall loan costs is crucial for prospective homebuyers. As rates continue to change, individuals must continuously evaluate their financial situations and mortgage options to make informed decisions in the real estate market.
The Role of a Real Estate Agent in a Rising Rate Environment
In an era of rising mortgage rates, the role of a real estate agent becomes increasingly crucial for prospective homebuyers. An experienced agent brings a wealth of knowledge about the local real estate market, which can significantly enhance a buyer’s ability to successfully navigate the complexities of purchasing a home amidst fluctuating rates.
One of the primary benefits of collaborating with a real estate agent during times of rising rates is their comprehensive understanding of the current market conditions. They possess insights into local inventory levels and price trends, allowing them to guide buyers towards the most suitable properties. With mortgage rates climbing, it is essential for buyers to identify homes that not only meet their needs but are also financially viable in the current economic landscape. A knowledgeable agent can provide valuable advice on timing and property selection, ultimately helping buyers make informed decisions.
Furthermore, real estate agents serve as skilled negotiators, advocating on behalf of their clients in a competitive market. Rising mortgage rates can prompt many potential buyers to withdraw from the market, leading to decreased competition for available properties. An agent’s negotiation skills are pivotal in capitalizing on this shift, potentially securing better purchase prices and favorable terms for homebuyers. Their expertise allows them to craft persuasive arguments and navigate offers, which are crucial in fostering successful negotiations even in a challenging financial climate.
In summary, engaging with a seasoned real estate agent can greatly benefit homebuyers during periods of rising mortgage rates. Their extensive market knowledge, coupled with strong negotiation capabilities, empowers buyers to find suitable properties while making prudent financial decisions. By leveraging the support of an experienced agent, homebuyers can navigate the complexities of the finance landscape more effectively, ultimately leading to more successful and satisfying home purchasing experiences.
Long-Term Considerations: Market Trends and Future Predictions
The recent rise in mortgage rates has led to significant shifts in the housing market, raising questions about the long-term financial implications for potential homebuyers. Understanding these trends is vital for making informed decisions, as current conditions may dictate future opportunities and challenges. Experts suggest that as finance becomes increasingly complex, market dynamics will evolve, influencing home purchasing behaviors and financing options.
Historically, rising mortgage rates can lead to decreased demand for homes, as higher borrowing costs discourage buyers. This cooling effect is often accompanied by a stabilization or potential decrease in home prices, which can offer opportunities for buyers who are financially prepared. Analysts predict that in the coming years, we may witness a market correction where home prices adjust downward, making housing more accessible to those who have previously been priced out.
Additionally, the finance landscape will continue to adapt, with alternative mortgage products gaining traction amidst rising interest rates. Adjustable-rate mortgages (ARMs) and other innovative financing solutions may appeal to buyers who wish to mitigate the long-term impact of current rate increases. Experts recommend that homebuyers remain vigilant, analyzing their options comprehensively and considering both immediate affordability and long-term financial stability.
Ultimately, the long-term implications of rising mortgage rates are multifaceted and require careful consideration. Economic factors such as inflation, employment rates, and Federal Reserve policies will shape housing and finance trends. Homebuyers should consult financial advisors, stay abreast of market news, and be prepared to pivot strategies as conditions develop.